Nvidia Earnings Beat and the Neocloud Financing Risk
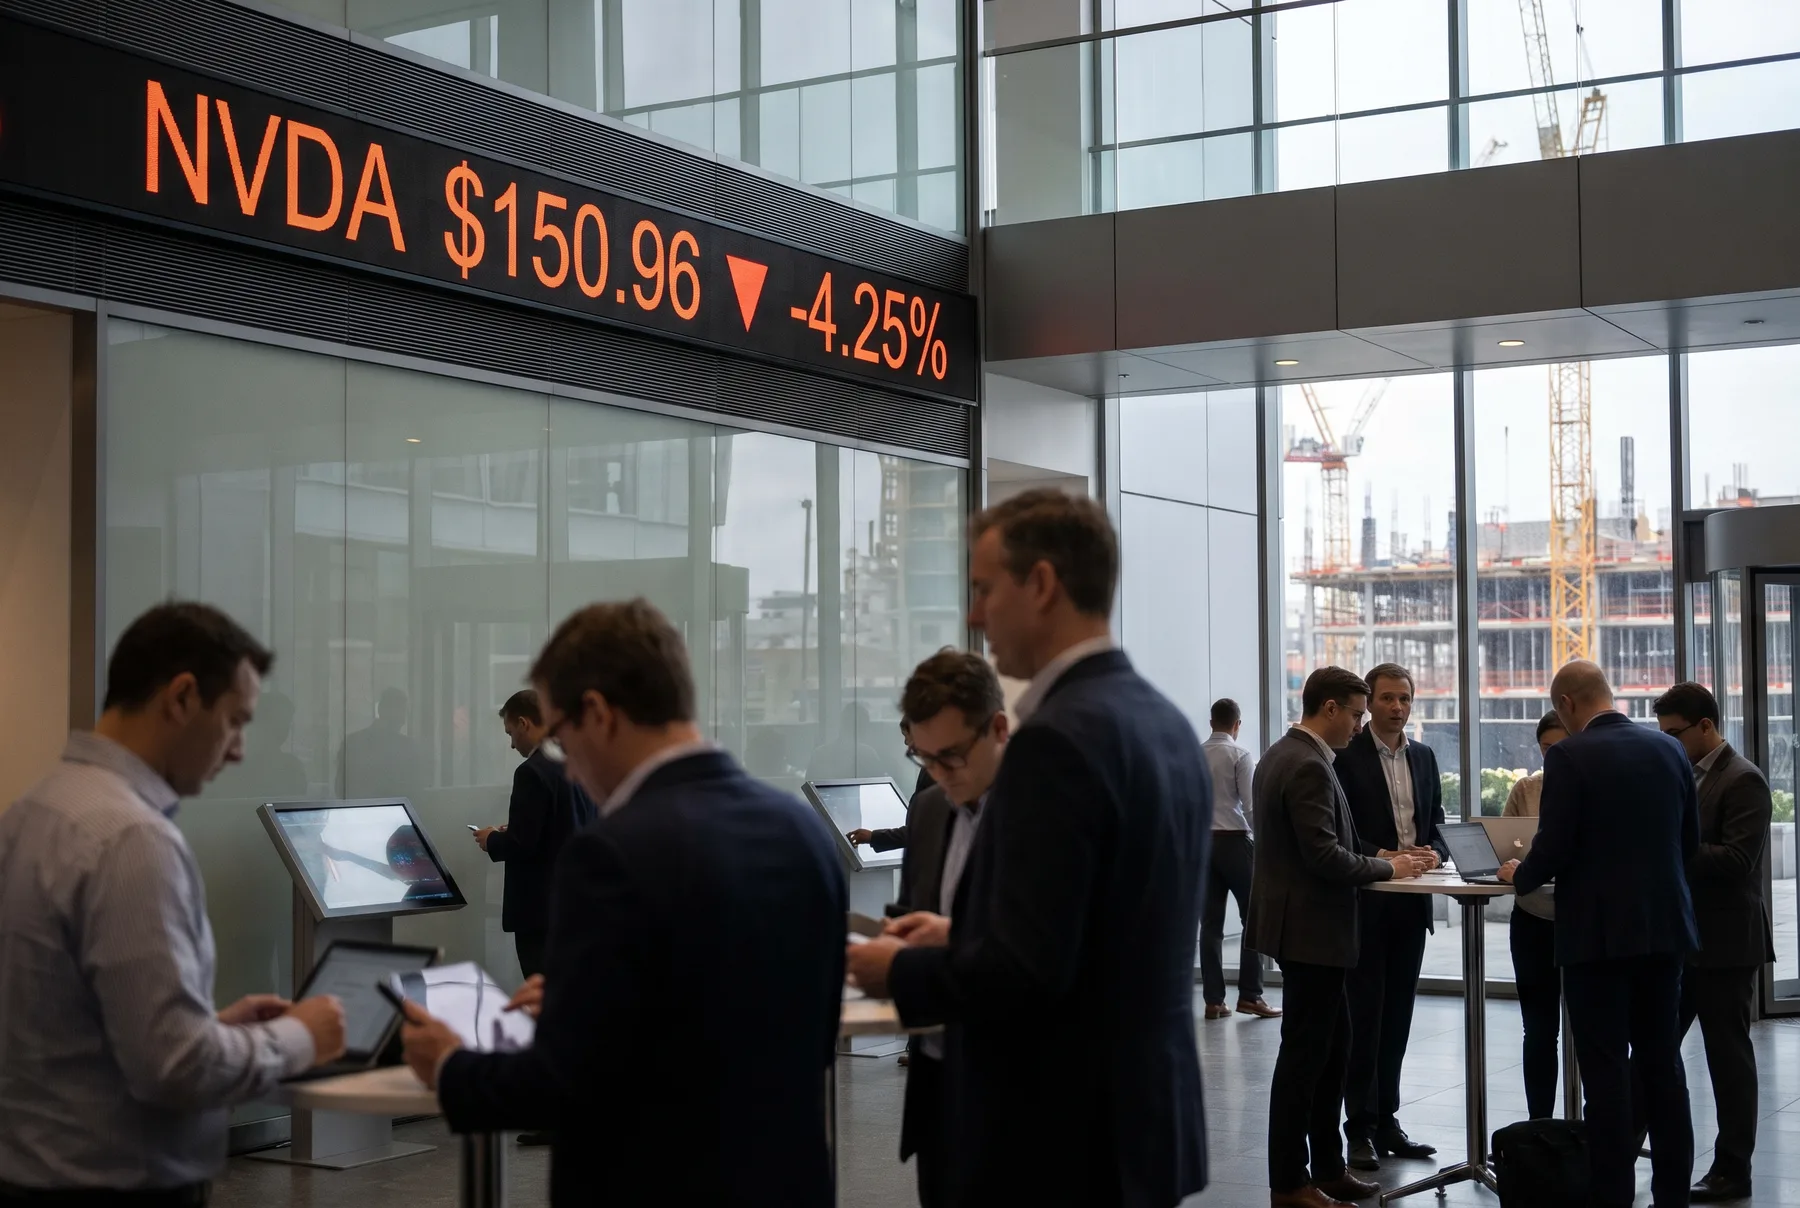
Nvidia passed all three of Joey's earnings tests, yet the stock closed at a 12-month low of $150.96, and the reason is a financing risk tied to its customers.
Listen to this article
On this page · 9 sections
Quick Answer: In my November 18, 2026 video, I said Nvidia passed all three earnings tests I'd set (revenue, guidance and gross margin), but a disclosure of about $32 billion in conditional commitments tied to customers who still need financing explains why Wall Street held back. As of the close on Wednesday, November 18, 2026, the shares were at $150.96, their lowest close in 12 months. My take in the video: the AI trade isn't over, but the easy money phase is.
Key takeaways
- In my November 18, 2026 video, I said Nvidia passed all three tests I'd set for revenue, guidance and gross margin.
- The risk I flagged in the video was about $32 billion in conditional commitments tied to neoclouds that still have to secure financing.
- Margins were the test I said I still had real concerns about, with management guiding lower for the next quarter before a gradual recovery.
- Nvidia closed at $150.96 on November 18, 2026, down 2.89% on the day and at its lowest close in 12 months.
- In the video, I argued Nvidia's demand numbers support the whole AI chip market, so one company winning doesn't mean the other has to lose.
Nvidia reported its quarterly results on Tuesday, November 17, 2026, and in my video on Wednesday, November 18, 2026, I went through the conference call line by line. The chipmaker passed every test I gave it in my previous Nvidia video. The stock still didn't race higher.
So what's holding it back? In the video, I pointed to a roughly $32 billion financing disclosure from the call. It raises the biggest question over the AI trade: how much of this demand depends on customers who still have to borrow the money to pay for it?
Where it stands now
As of the close on Wednesday, November 18, 2026, the day the video came out, NVIDIA shares were at $150.96 and Advanced Micro Devices shares were at $530.14. There's no change since the video yet.
- NVIDIA fell 2.89% on November 18, 2026, its lowest close in 12 months and 38.0% below its 52-week high.
- Trailing P/E of 16.2x and forward P/E of 9.1x as of the close on November 18, 2026.
- Trailing 12-month revenue of $302.97 billion, with latest-quarter revenue up 105.9% from a year earlier.
Chart Equity · NVDA
NVDA, last 6 months
May 19, 2026 to Nov 18, 2026. Change is from the close just before the chart starts.
150.96
-32.10% over 6 months
Did Nvidia pass the three earnings tests?
Yes, all three. In the video, I set three bars going in: revenue, fourth-quarter guidance and adjusted gross margin. The company cleared every one of them, so it's three for three, with one catch on margins. Here's how each result stacked up against the bar I'd set.
| Test | My bar | Result |
|---|---|---|
| Revenue | $109 billion | $115.8 billion |
| Fourth-quarter guidance | $125 billion | $130 billion |
| Adjusted gross margin | roughly 74% | 74.9% |
Every line beat my bar, though margins cleared it by the thinnest gap.
| Test (as I laid it out in the video) | My bar | Result |
|---|---|---|
| Revenue | Beat $109 billion | $115.8 billion, up 103% |
| Fourth-quarter guidance | Above $125 billion | $130 billion |
| Adjusted gross margin | Hold around 74% | 74.9% |
The guidance quarter includes an extra reporting week, but it still cleared Wall Street's expectations comfortably. Adjusted earnings of $2.68 a share sat on top of $65.3 billion in quarterly net income.
Watch how steep the climb gets after fiscal 2023.
Real data · NVDA
Nvidia revenue, last 5 fiscal years
Annual, USD. Latest fiscal year ended January 25, 2026.
$215.9B
+68.3% a year since FY2022
| Fiscal year | revenue |
|---|---|
| FY2022 | $26.9B |
| FY2023 | $27.0B |
| FY2024 | $60.9B |
| FY2025 | $130.5B |
| FY2026 | $215.9B |
How big is the demand Nvidia described?
Bigger than most people expected. In the video, I said the interim CEO raised expected revenue growth for fiscal 2028 to about 75%, up from more than 70%. If Nvidia hits its fourth-quarter guidance, fiscal 2027 revenue lands near $424 billion.
That's close to three quarters of a trillion dollars in annual sales. So where are the folks screaming AI bubble? Customers are practically fighting over computing capacity.
Management put the broader cloud industry's backlog at about $2.5 trillion, up from $2 trillion three months earlier. But that's the industry's backlog, not guaranteed Nvidia orders. Nvidia still has to win its share.
Why older chips are getting more expensive to rent
This detail stood out most to me. Some older-generation GPUs were renewed under multi-year rental deals at up to twice their original prices, and rental rates on a newer generation rose more than 60% since launch. Normally old tech gets cheaper. Here, more powerful AI models are eating so much computing power that customers are paying up for previous-generation chips.
Based on those signals, I said I don't believe the AI infrastructure boom is over. There's a problem, though.
What is the $32 billion financing risk?
In the video, I said Nvidia disclosed about $32 billion in conditional commitments tied to neocloud arrangements. Those depend on smaller AI infrastructure companies getting financing, buying equipment and bringing computing capacity online. If those conditions aren't met, Nvidia says some commitments could change, be reduced or be eliminated.
Neoclouds run data centers packed with advanced computing equipment and rent that capacity to AI developers. Many are growing faster than their balance sheets can support. If lenders stop writing checks, you could end up with customers desperate for chips but unable to pay for them.
"Nvidia isn't just selling chips anymore. It's also helping finance parts of the AI infrastructure boom."
That's the circular financing concern. Nvidia supports an AI company, that company uses financing to buy Nvidia chips, and those purchases feed Nvidia's revenue. I was clear this doesn't mean anything illegal or that the revenue isn't real. The question is how much demand survives without that support, and that helps explain why Wall Street wasn't ready to bid the stock back up. Our breakdown of why the AI demand data still looks strong covers the other side.
Are Nvidia's margins starting to slip?
A little, and it was the test I said I still had real concerns about. Adjusted gross margin came in at 74.9%, which cleared my bar, but management expects it to slip to 71% to 72% next quarter. That's a step down, even if they're framing it as temporary.
They called that the bottom, with a gradual recovery toward 72% or 73% expected in 2028.
Nvidia is still scoring 10 goals a game, but investors worry the team will start letting more in. The reasons on the call were rising costs for advanced memory and the complexity of ramping the next-generation chip platform. Nvidia has already pushed through price increases that management expects to offset those costs.
What about the CEO change?
Management said it doesn't intend to reinstate the former CEO. The encouraging part is that the team he built is still delivering, and the interim CEO laid out an even stronger long-term outlook.
"The championship hockey team has lost its legendary coach, but the players clearly haven't forgotten how to play."
Where could Nvidia stock go from here?
The honest answer I gave in the video: no one knows. The mood reminded me of software stocks in the spring, when Wall Street treated a whole sector like it was worthless.
What caught my attention was the gap between that 75% growth forecast and how the stock was trading. If the company delivers and confidence returns, I said there's a defensible path higher. That hinges on management hitting its growth and profitability assumptions.
To check the valuation, growth, insider activity and risks yourself, the free NVDA Stock Audit puts it on one page. Our NVIDIA Stock Audit deep dive goes through the full scorecard.
Does Nvidia's report change the case for AMD?
Not in my view. AMD's data center business generated $8.5 billion last quarter, up 97%, on total revenue of $13.4 billion, with about $17 billion expected next quarter. AMD doesn't need to beat Nvidia to do well. It just needs to capture a meaningful piece of a growing market.
When I made the video on November 18, 2026, I owned AMD shares. I may have bought or sold since. For the backstory on AMD's recent swing, see why AMD stock fell 17% on Thursday.
Is the AI trade over?
No, but it's changed.
"Is the AI trade over? Absolutely not. But I think the easy money phase of AI is over."
The market is wary of semiconductor cycles. Industry sales fell 8.2% in 2023 before bouncing back 19.1% in 2024. But Nvidia's data center business just grew 110%, and it made $65 billion of profit in one quarter. That's an earnings machine, not a speculative startup. It isn't immune to a downturn, but investors may be pricing in a slowdown that hasn't shown up yet.
"You need to recognize when a business is getting stronger while investors are panicking."
What's next for Nvidia stock?
In the video, I said to watch three things. Are big tech companies cutting AI spending? No clear sign yet. Are margins deteriorating? Management outlined a recovery path. Can customers keep financing new infrastructure? That's the big unknown.
If those risks get worse, I said I'd become more cautious. Nvidia's next report date isn't confirmed yet. AMD's next report is estimated for Tuesday, February 2, 2027, on Yahoo Finance's earnings calendar, an early read on whether the demand is holding up.
Related Reading
Frequently Asked Questions
What is Nvidia's P/E ratio after earnings?
As of the close on November 18, 2026, Nvidia traded at a trailing P/E of 16.2x on trailing 12-month EPS of $9.31. The forward P/E was 9.1x, based on the consensus estimate of $16.61 for next fiscal year. A forward multiple that low only holds up if those earnings estimates do, which is why the financing question matters.
How has Nvidia stock done compared with the S&P 500?
Poorly over the past year. Nvidia shares fell 16.8% in the year to the close on November 18, 2026, while the S&P 500 gained 10.7% over the same stretch. The stock's highest close in that window was $239.24 on October 6, 2026, so the drop to $150.96 came in about six weeks.
What do analysts think of Nvidia stock?
Most are positive. Of the analysts covering it, 46 rate it Buy or Strong Buy, 15 rate it Hold and 2 rate it Sell. Among 55 analysts with price targets, the average target is $253.67, with a range from $130.00 to $450.00. Targets are opinions, and that wide spread shows how much disagreement there's about the AI cycle.
Does Nvidia carry a lot of debt?
Not relative to its cash. In its latest quarter, Nvidia reported $62.47 billion in total cash against $38.86 billion in total debt, and its current ratio is 4.08. It generated $96.68 billion of free cash flow in fiscal 2026. The balance-sheet worry from the earnings call is about its customers' financing, not Nvidia's own.
Did Nvidia beat earnings estimates?
Yes. For the quarter reported on November 17, 2026, Nvidia posted EPS of $2.68 against the consensus estimate of $2.49, a 7.6% surprise. It's beaten the estimate in each of the four most recent quarters, including $2.22 against $2.09 in the quarter reported on August 26, 2026, so the beat itself wasn't a surprise to the market.